

Kayonews-If you are launching a startup in the U.S. in 2026, business loans can provide capital for equipment, inventory, working capital, technology and other startup expenses. However, lenders generally look closely at credit history, repayment capacity, business plans and financial projections.
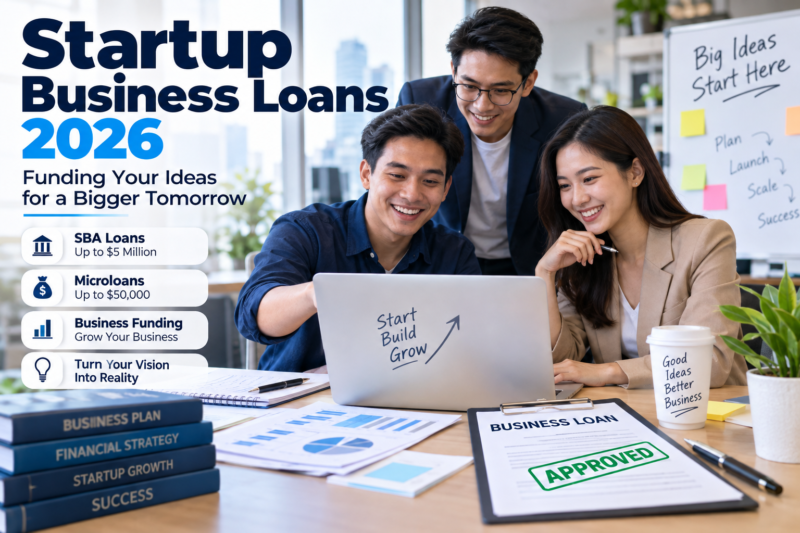
One major option is the SBA 7(a) loan. The program supports financing of up to $5 million and can be used for working capital, equipment, supplies, real estate and even starting a business. SBA says borrowers must generally operate a for-profit business in the United States, meet size requirements and demonstrate the ability to repay.
For smaller startups, the SBA Microloan program may be relevant. Microloans can provide up to $50,000, with the average loan around $13,000. Funds can generally cover working capital, inventory, supplies, furniture and equipment. The maximum repayment period is seven years, while rates are generally between 8% and 13%.
Another option is SBA-backed financing through the 504 program, particularly when the startup needs capital for major fixed assets such as buildings or equipment. SBA’s current program information lists 504 financing from $25,000 to $5.5 million, with fixed-rate financing and longer repayment periods for qualifying projects.
A significant 2026 development is that eligible businesses can now potentially combine SBA 7(a) and 504 financing for up to $10 million in cumulative SBA-backed funding. The change became effective July 4, 2026.
Startup Business Loan Requirements
Before applying, prepare:
- Business plan
- Detailed loan amount and use of funds
- Personal and business credit information
- Revenue or financial projections
- Cash-flow projections
- Business formation documents
- Tax and financial records, when available
- Information about collateral, if required
The SBA specifically recommends having a business plan, knowing exactly how much funding is required, documenting how the money will be used and preparing financial projections.
Startup Loan Options in 2026
| Loan option | Potential amount | Common use |
|---|---|---|
| SBA 7(a) | Up to $5 million | Working capital, equipment, business acquisition |
| SBA Microloan | Up to $50,000 | Inventory, supplies, equipment |
| SBA 504 | Up to $5.5 million | Buildings and major equipment |
| SBA 7(a) + 504 | Up to $10 million cumulative for eligible borrowers | Larger expansion and capital needs |
| Conventional bank loan | Varies | Startup and business expenses |
| Business line of credit | Varies | Short-term working capital |
Interest rates and approval requirements vary by lender. SBA-backed loans do not mean automatic approval; lenders still evaluate the applicant’s creditworthiness and ability to repay.
How to Improve Your Approval Chances
Start by calculating exactly how much capital you need. Avoid requesting substantially more than the business can reasonably justify.
Next, create realistic revenue and expense projections. A lender needs to understand where repayment will come from.
You should also compare multiple lenders. SBA’s Lender Match allows businesses to submit information about their financing needs and potentially receive interested lenders. SBA says participating lenders can be compared on rates, terms and fees.
FAQ
Can I get a business loan for a startup with no revenue?
Potentially. Startup financing can be available, but lenders may place greater emphasis on the owner’s credit, business plan, projections, collateral and ability to repay.
How much can a startup borrow from the SBA?
The SBA 7(a) program has a maximum loan amount of $5 million. Eligible borrowers may also potentially combine 7(a) and 504 financing under the 2026 rules for up to $10 million cumulatively.
What is the smallest SBA startup loan?
SBA Microloans can provide financing of up to $50,000, and the average microloan is approximately $13,000.
Do startups need collateral?
Collateral requirements depend on the loan, lender and circumstances. SBA notes that some programs have situations where collateral is not required, while individual lenders may have their own requirements.
Is an SBA loan guaranteed?
No. An SBA guarantee supports the lender, but the borrower still must meet eligibility and underwriting requirements.
Can a startup use an SBA loan for working capital?
Yes. SBA 7(a) financing can be used for short- and long-term working capital, while Microloans can also support working capital. (*)