

Kayonews-Mortgage rates in Norway are an important factor for anyone planning to buy a home. Even a small rate difference can affect monthly payments and total borrowing costs.
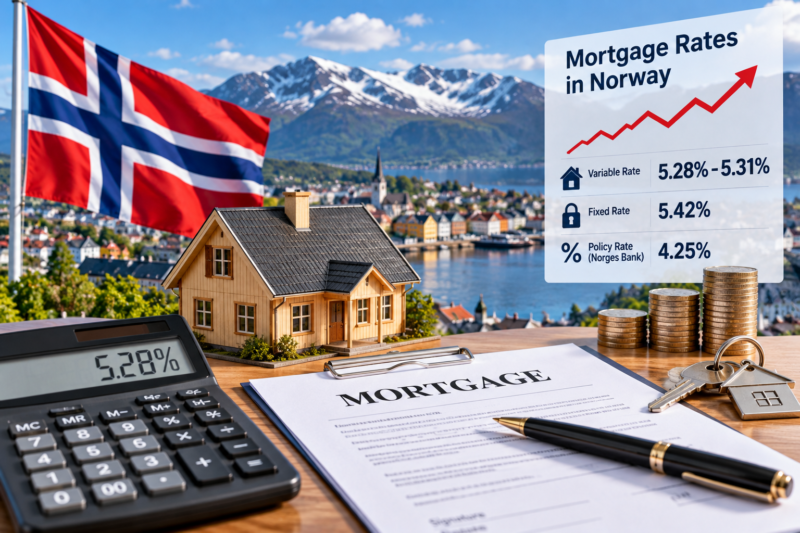
As of September 2026, Norges Bank’s policy rate is 4.25%. The central bank’s next rate decision is scheduled for September 24, 2026.
For homebuyers, however, the mortgage rate offered by a bank can differ from the central bank’s policy rate. Banks consider factors such as loan-to-value, income, debt and the borrower’s financial profile.
What Are Mortgage Rates in Norway?
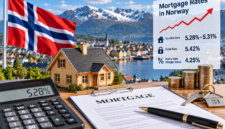
Official statistics from Statistics Norway show that the average interest rate on outstanding residential loans to households reached 5.31% in July 2026.
For new repayment loans secured against residential property, the average rate was 5.28%, while new fixed-rate repayment loans averaged 5.42%.
These figures are averages across banks and mortgage companies. The rate available to an individual borrower can therefore be higher or lower.
Fixed vs Variable Mortgage Rates
Norwegian homebuyers can encounter both floating and fixed mortgage rates.
A floating-rate mortgage can change when market conditions and banks’ pricing change. This can make monthly payments less predictable.
A fixed-rate mortgage provides greater payment certainty for the agreed fixed period. However, borrowers should carefully review the terms before choosing this option.
Official Statistics Norway data shows that floating-rate mortgages account for the overwhelming majority of Norwegian household mortgages. In the second quarter of 2026, 95.8% of mortgages had floating interest rates, while 4.2% had fixed rates.
Why Do Mortgage Rates Change?
Mortgage rates are influenced by several factors.
One important factor is the Norges Bank policy rate. Changes in monetary policy can affect banks’ funding costs and ultimately influence lending rates.
Competition between banks also matters. Norges Bank reported that banks experienced stronger competition and declining lending spreads for residential mortgages during the second quarter of 2026.
Borrowers should therefore compare mortgage offers instead of assuming that every bank charges the same rate.
What Mortgage Rate Can You Get?
Your personal mortgage rate depends on your financial circumstances and the bank’s pricing.
Important factors can include:
- Loan-to-value ratio
- Income
- Existing debt
- Employment situation
- Property value
- Loan amount
- Repayment period
- Banking relationship
- Credit assessment
A borrower with a lower loan-to-value ratio may receive different pricing from someone borrowing a larger percentage of the property’s value.
Mortgage Rates and Loan-to-Value
Loan-to-value is an important consideration when applying for a mortgage.
For example, a NOK 5 million property financed with a NOK 4 million mortgage has an 80% loan-to-value ratio.
A borrower financing NOK 4.5 million against the same property would have a 90% loan-to-value ratio.
The difference can affect both borrowing risk and the mortgage rate offered by a lender.
How Much Does a Mortgage Payment Cost?
Consider a hypothetical mortgage of NOK 4 million with a 25-year repayment period.
At an interest rate of 5%, the estimated monthly principal and interest payment would be around NOK 23,400.
At 6%, the estimated payment would rise to around NOK 25,800.
This illustrates why mortgage rates matter. The actual payment will depend on the bank’s rate, repayment structure, fees and loan conditions.
How to Compare Mortgage Rates in Norway
Homebuyers should compare more than the headline interest rate.
Look at the effective interest rate, fees, repayment period and other conditions attached to the loan.
The effective rate can provide a better picture of the overall borrowing cost because it takes relevant charges into account.
Norway’s Financial Supervisory Authority also publishes information on mortgage-market reference rates and lending conditions.
Can You Get a Lower Mortgage Rate?
There are several ways borrowers may improve their mortgage offer.
First, compare multiple banks before accepting an offer.
Second, consider whether a larger down payment can reduce the loan-to-value ratio.
Third, review your mortgage periodically. Market competition can change the pricing available to borrowers.
Norges Bank reported that residential mortgage lending spreads declined during the second quarter of 2026, indicating changes in competition and bank pricing.
Mortgage Rates for Foreigners in Norway
Foreigners may be able to obtain mortgage financing in Norway.
However, requirements can differ depending on the bank and the applicant’s circumstances.
Banks may consider Norwegian income, employment, residence status, existing debt, down payment and the property being purchased.
Foreign buyers should contact lenders directly and request their current mortgage requirements before committing to a property purchase.
Should You Choose a Fixed or Floating Rate?
There is no single mortgage structure that suits every borrower.
A floating rate provides exposure to future rate changes. Payments can decrease if rates fall, but they can also increase when rates rise.
A fixed rate provides greater certainty for the fixed period. However, the borrower may have less flexibility if market rates subsequently fall.
The decision should be based on the household’s finances, risk tolerance and expected time in the property.
How to Calculate Your Mortgage Cost
Before applying, use a mortgage calculator to estimate different scenarios.
Enter:
- Property price
- Down payment
- Mortgage amount
- Interest rate
- Repayment period
Then compare the monthly payment at several interest-rate levels.
For example, testing rates of 4%, 5%, 6% and 7% can show how sensitive the household budget is to interest-rate changes.
Norway Mortgage Rates in 2026
The latest official monthly data from Statistics Norway shows that outstanding residential mortgage rates averaged 5.31% in July 2026, while new residential repayment loans averaged 5.28%.
Meanwhile, Norges Bank’s policy rate stood at 4.25% in September 2026.
These numbers should not be treated as a guaranteed mortgage offer. Individual banks can offer different rates based on the borrower and loan conditions.
Frequently Asked Questions
What is the current mortgage rate in Norway?
Statistics Norway reported an average rate of 5.31% on outstanding residential loans to households in July 2026. New repayment loans averaged 5.28%.
What is the Norges Bank policy rate?
The Norges Bank policy rate is 4.25% as of September 2026.
Are mortgage rates in Norway fixed or variable?
Both options exist, but floating-rate mortgages dominate the Norwegian market. Statistics Norway reported that 95.8% of mortgages had floating rates in the second quarter of 2026.
Can foreigners get a mortgage in Norway?
Foreigners may qualify for mortgage financing, but approval depends on the lender and the applicant’s financial circumstances.
How can I get a lower mortgage rate?
Compare several lenders, maintain a strong financial profile and consider whether a lower loan-to-value ratio could improve your offer.
Does the Norges Bank rate determine mortgage rates?
The policy rate influences financial conditions, but banks set their own mortgage pricing based on funding costs, competition, risk and other factors.
Should I choose a fixed mortgage rate?
A fixed rate can provide greater payment certainty, while a floating rate exposes borrowers to changing market rates. Compare the full loan terms before deciding.
Final Takeaway
Mortgage rates are one of the most important costs to consider when buying a home in Norway.
The latest official data shows mortgage rates remain significantly above the Norges Bank policy rate. Individual borrowers can receive different offers depending on their finances, property and loan-to-value ratio.
Before choosing a mortgage, compare the effective interest rate, fees, repayment period and flexibility. A difference of even a few tenths of a percentage point can become significant over a long mortgage term. (*)
Editor : Fanda Yosephta