

Kayonews-Homeowners insurance remains an important financial protection for U.S. homeowners in 2026. A standard policy can protect the home, belongings, and personal liability. However, coverage depends on the policy terms, limits, deductibles, and covered perils. Understanding these details can help homeowners compare insurance quotes more effectively.
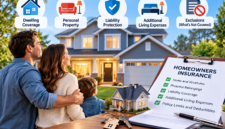
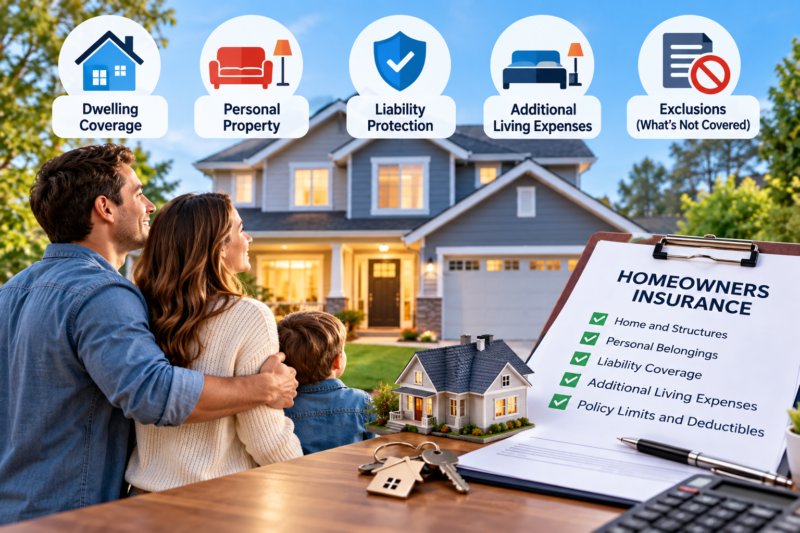
A standard homeowners policy generally provides dwelling coverage for the house and attached structures. This can include fixtures and permanently installed systems. Coverage may help pay for repairs or rebuilding after a covered event. The Insurance Information Institute recommends having enough dwelling coverage to rebuild the home rather than matching its market value.
Homeowners insurance can also cover other structures on the property. Examples include detached garages, sheds, fences, and similar structures. Personal property coverage can protect belongings such as furniture, clothing, electronics, and appliances. Certain valuable items may have special limits, so homeowners should review their policy carefully.
Personal liability is another important part of homeowners insurance. It can help protect a homeowner when they are legally responsible for injuries or property damage involving another person. Policies can also include medical payments coverage for certain injuries involving guests. Liability limits should be reviewed based on the homeowner’s financial situation and potential risks.
Additional living expenses can become important after a covered loss makes a home unlivable. This coverage may help pay certain extra costs while repairs are underway. Covered expenses can include temporary lodging and some additional meal costs. Policies may impose dollar or time limits, so homeowners should check their specific contract.
One common mistake is assuming homeowners insurance covers every type of disaster. Standard policies generally exclude certain risks, including flooding and earthquakes. Flood damage usually requires separate flood insurance, while earthquake coverage may require a separate policy or endorsement. Maintenance problems, infestations, and some other losses can also be excluded.
The deductible can also affect the cost of homeowners insurance. A deductible is the amount the policyholder generally pays before insurance contributes to a covered loss. A higher deductible can reduce the premium, while a lower deductible can increase the premium. Homeowners should compare both the deductible and coverage limits when reviewing insurance quotes.
Before choosing a homeowners insurance company in 2026, compare quotes using similar coverage limits and deductibles. Check dwelling coverage, personal property limits, liability protection, exclusions, additional living expenses, and available discounts. Also review whether valuable possessions require additional coverage. Comparing the full policy instead of only the monthly premium can help homeowners find protection that better fits their needs. (*)
Editor : Fanda Yosephta