

Kayonews-Home insurance has become one of the biggest recurring costs for homeowners in the United States.
Recent 2026 data shows just how significant the expense can be. MarketWatch reported that the average single-family homeowner with a mortgage was paying about $209 per month, or roughly $2,500 per year, in June 2026. Premiums have risen sharply in recent years, although costs vary substantially by location and risk.
That makes choosing the right homeowners insurance company more important than simply finding the cheapest quote.
A lower premium may come with higher deductibles or less favorable coverage. Meanwhile, a more expensive policy may provide stronger protection, better claims service or coverage options that are particularly valuable in high-risk areas.
Below, we compare some of the best home insurance companies in 2026 based on factors including price, coverage options, claims satisfaction, complaints and specialized customer needs.
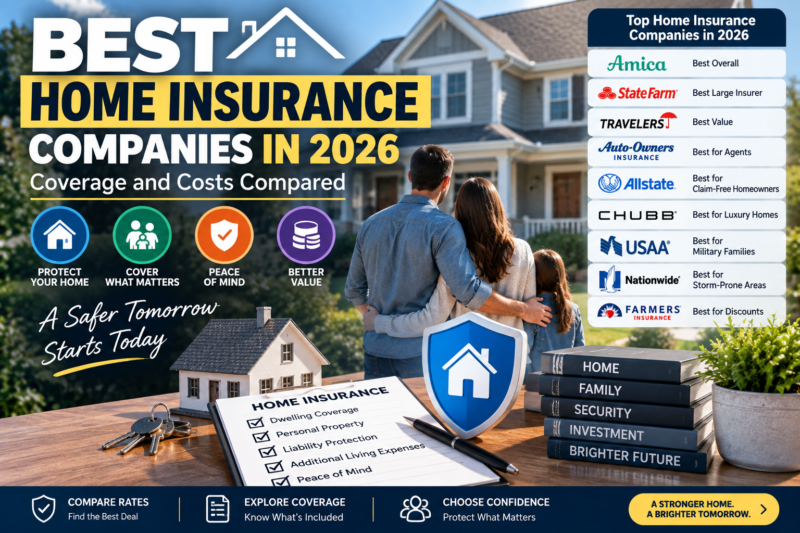
Best Home Insurance Companies in 2026
Quick comparison
| Company | Best for | Average annual rate* |
|---|---|---|
| Amica | Best overall | ~$1,510–$1,707 |
| State Farm | Large national insurer | ~$1,761 |
| Travelers | Strong overall value | Varies |
| Auto-Owners | Independent agents | ~$3,206 |
| Allstate | Claim-free homeowners | ~$2,352 |
| Chubb | Luxury homes | ~$3,790 |
| USAA | Military families | ~$2,418 |
| Nationwide | Storm-prone areas | ~$3,490 |
| Farmers | Discounts | ~$2,895 |
*Average premiums vary by methodology, coverage amount, location and customer profile. These figures should not be treated as personalized quotes. LendingTree’s 2026 comparison, for example, uses a $400,000 coverage benchmark.
1. Amica — Best Overall Home Insurance
Best for: Homeowners who prioritize a combination of price, coverage and customer experience.
Amica stands out in several 2026 comparisons.
Insurance.com ranked Amica No. 1 overall in its 2026 homeowners insurance survey, with an average annual premium of about $1,510, compared with a national average of $2,543 in that analysis. It also reported that Amica had a low complaint ratio and an A+ AM Best financial-strength rating.
LendingTree also selected Amica as its best homeowners insurance company overall, reporting an average annual rate of approximately $1,707 under its methodology.
Why consider Amica?
- Competitive premiums
- Strong customer satisfaction
- Strong financial-strength rating
- Broad homeowners coverage
- Available discounts and policy options
Best for
Homeowners looking for a well-rounded national insurance option rather than simply the lowest possible quote.
2. State Farm — Best Large National Insurer
Best for: Homeowners who want a large insurer and access to local agents.
State Farm is one of the biggest insurance brands in the United States and offers homeowners coverage through its national network.
LendingTree ranked State Farm as its best large insurance company in its 2026 comparison, with an average annual rate of about $1,761 under its methodology.
A major advantage of a large insurer is the ability to combine multiple insurance products.
For example, homeowners may be able to bundle:
- Home insurance
- Auto insurance
- Life insurance
- Personal liability coverage
Bundling can simplify insurance management and may reduce the total cost.
Best for
Homeowners who prefer working with a recognizable national insurer and local agent.
3. Travelers — Best for Overall Value
Best for: Homeowners looking for competitive pricing and strong coverage options.
Travelers made a significant jump in Insurance.com’s 2026 rankings, reaching second place in its national comparison.
Insurance.com gave Travelers an overall score of 4.30, highlighting below-average rates, a top-tier AM Best rating and strong service performance.
Potential advantages
- Competitive pricing
- Strong financial strength
- Broad coverage options
- National availability
- Multiple discounts
Travelers can be particularly attractive to homeowners who want a balance between price and coverage.
4. Auto-Owners — Best for Independent Agents
Best for: Homeowners who want to work with an independent insurance agent.
Auto-Owners is different from some of the largest national insurers because it relies heavily on independent agents.
LendingTree selected Auto-Owners as its best insurer for working with an independent agent. Its comparison reported an average annual rate of about $3,206 under its $400,000 coverage methodology.
An independent agent can be useful when comparing several insurance carriers rather than receiving a quote from only one company.
Best for
Homeowners who prefer personalized assistance and want an agent to help compare coverage options.
5. Allstate — Best for Claim-Free Homeowners
Best for: Homeowners with a history of few or no claims.
Allstate is one of the largest homeowners insurance brands in the country.
LendingTree selected Allstate as its best option for claim-free homeowners, reporting an average annual premium of approximately $2,352 under its comparison methodology.
The company offers a broad selection of coverage and discount options.
Best for
Homeowners who want a large national insurer and may benefit from claim-related savings or discounts.
6. Chubb — Best for Luxury Homes
Best for: High-value homes and homeowners with expensive belongings.
Luxury properties often require different insurance considerations.
A standard policy may not provide enough coverage for:
- High-value jewelry
- Fine art
- Collectibles
- Expensive electronics
- Custom construction
- High-end furnishings
LendingTree selected Chubb as its best insurer for luxury homes. Its 2026 comparison reported an average annual rate of approximately $3,790 under its methodology.
The higher premium can make sense for homeowners whose property and possessions require specialized coverage.
Best for
High-net-worth homeowners who need higher limits and specialized protection.
7. USAA — Best for Military Families
Best for: Eligible members of the military community and their families.
USAA is a specialized financial-services and insurance provider serving military members, veterans and eligible family members.
Insurance.com reported USAA with a 4.49 overall rating and 4.53 customer satisfaction rating in its 2026 comparison.
LendingTree reported an average annual rate of approximately $2,418 in its 2026 comparison.
Best for
Eligible military members, veterans and their families looking for specialized insurance services.
8. Nationwide — Best for Storm-Prone Areas
Best for: Homeowners who need to pay close attention to severe-weather risks.
LendingTree selected Nationwide as its best homeowners insurance company for storm-prone areas.
Its 2026 comparison reported an average annual premium of about $3,490 under its methodology.
Homeowners in areas exposed to hurricanes, windstorms, hail or severe weather should pay particularly close attention to deductibles and exclusions rather than comparing premiums alone.
Important
A policy may treat wind, hail, hurricane damage and flooding differently.
That distinction can become extremely important after a major storm.
9. Farmers — Best for Discounts
Best for: Homeowners who want to explore multiple discount opportunities.
Farmers was selected by LendingTree as its best option for discounts.
The 2026 comparison reported an average annual premium of approximately $2,895 under its methodology.
Potential discounts can vary based on factors such as:
- Home security systems
- Newer roofs
- Bundled insurance
- Claim-free history
- Protective devices
- Payment options
Always confirm which discounts are actually available in your state.
How Much Does Homeowners Insurance Cost in 2026?
Homeowners insurance prices vary dramatically across the United States.
Recent 2026 reporting shows the average homeowner with a mortgage paying roughly $2,500 per year, or about $209 per month, based on June 2026 data.
But an individual homeowner can pay considerably less or considerably more.
Your quote may depend on:
- State
- ZIP code
- Home value
- Replacement cost
- Age of the property
- Roof age
- Construction materials
- Credit-based insurance score where permitted
- Claims history
- Deductible
- Coverage limits
- Local crime levels
- Wildfire risk
- Hurricane risk
- Flood risk
- Distance to emergency services
This is why online national averages should never be interpreted as a personalized insurance quote.
What Does Homeowners Insurance Cover?
A standard homeowners policy generally provides several categories of protection.
The National Association of Insurance Commissioners identifies common coverage categories including dwelling, other structures, personal property, loss of use, personal liability and medical payments.
1. Dwelling coverage
This protects the physical structure of your home against covered losses.
It can include:
- Walls
- Roof
- Floors
- Built-in appliances
- Attached structures
The coverage limit should generally be sufficient to rebuild the home rather than simply match its market value.
2. Other structures
This can cover structures that are not physically attached to your house.
Examples include:
- Detached garages
- Sheds
- Fences
- Certain other structures
3. Personal property
This covers belongings such as:
- Furniture
- Clothing
- Electronics
- Appliances
- Personal possessions
Certain expensive items may require additional coverage or higher limits.
4. Loss of use
If your home becomes uninhabitable after a covered loss, your policy may help pay certain additional living expenses.
These can include temporary accommodation and other expenses above your normal living costs, subject to policy limits.
5. Personal liability
Liability coverage can help protect you financially if you are legally responsible for covered bodily injury or property damage involving another person.
6. Medical payments
Some policies also provide limited coverage for medical expenses involving people injured on your property, subject to the policy terms.
What Does Home Insurance NOT Cover?
This is one of the most important questions to ask before buying a policy.
Homeowners insurance does not cover every possible type of damage.
Common exclusions can include:
- Flooding
- Earthquakes
- Landslides
- Certain types of water damage
- Wear and tear
- Neglect
- Pest damage
- Certain business-related losses
The exact exclusions depend on the policy.
The NAIC notes that flood and earthquake damage are generally excluded from standard homeowners policies.
Does Homeowners Insurance Cover Flood Damage?
Usually, no.
The Federal Emergency Management Agency’s National Flood Insurance Program states that most homeowners insurance policies do not cover flood damage.
That means homeowners in flood-prone areas may need a separate flood insurance policy.
Flooding can occur even outside traditionally high-risk flood zones.
According to FloodSmart, almost one-third of NFIP claims from 2014 through 2024 came from low- to moderate-risk areas.
What About Hurricane Damage?
Hurricanes can create multiple types of damage, and insurance treatment can differ.
For example:
Wind damage may be covered by homeowners insurance.
Flood or storm-surge damage generally requires separate flood insurance.
The NAIC notes that hurricane-related windstorm or hail damage is usually covered, while flood and storm surge are generally not covered by standard homeowners insurance.
This distinction can be critical for homeowners along the U.S. Gulf and Atlantic coasts.
Replacement Cost vs. Actual Cash Value
When comparing policies, pay attention to how your property will be valued after a loss.
Replacement cost
Replacement-cost coverage generally aims to pay the cost of replacing damaged property with comparable new property, subject to policy limits and terms.
Actual cash value
Actual cash value generally considers depreciation when determining the value of damaged property.
For example, a five-year-old roof may be worth substantially less under an actual-cash-value calculation than the cost of installing a new roof.
This distinction can have a major impact on claim payments.
How Much Home Insurance Do You Need?
Do not simply insure your home for its current market price.
The amount needed to rebuild a home can differ significantly from its real-estate market value.
The NAIC recommends that dwelling coverage be sufficient to cover the cost of fully rebuilding the insured home.
Your coverage calculation should consider:
- Local construction costs
- Square footage
- Building materials
- Custom features
- Attached structures
- Labor costs
- Current rebuilding prices
Consider reviewing the coverage after major renovations or additions.
How Deductibles Affect Your Premium
A deductible is the amount you are responsible for paying before insurance covers the remaining covered loss.
Generally:
Higher deductible = lower premium
Lower deductible = higher premium
The NAIC notes that a lower deductible generally results in a higher premium.
For example, choosing a $2,500 deductible instead of $1,000 could reduce your premium, but you would need to pay more out of pocket after a covered claim.
The best deductible is one you could realistically afford after a major loss.
How to Lower Your Home Insurance Cost
Homeowners have several ways to potentially reduce premiums.
Shop around
Compare quotes from several insurers.
Prices can vary substantially for the same property.
Bundle policies
Combining home and auto insurance with one company may produce a discount.
Increase your deductible
A higher deductible can lower your premium, provided you can afford the additional out-of-pocket cost.
Improve home security
Security systems, smoke detectors and other protective devices may qualify for discounts with some insurers.
Upgrade your roof
A newer, more resilient roof can potentially reduce risk and improve eligibility for certain discounts.
Maintain a claims-free record
Some insurers offer discounts or better pricing to homeowners with limited claims histories.
Review your coverage every year
Your insurance needs can change after:
- Renovations
- Major purchases
- New valuables
- Changes in household income
- Changes in local risk
- Significant changes in property value
Why Home Insurance Prices Are Rising
The U.S. home insurance market has been under significant pressure.
MarketWatch reported that average premiums reached a record level in June 2026, with costs nearly 80% higher than in 2020 in its analysis.
Several factors can influence insurance costs:
- Severe weather
- Wildfires
- Hurricanes
- Construction costs
- Labor costs
- Home-repair expenses
- Reinsurance costs
- Local insurance regulations
- Claims frequency
These factors can affect insurers differently from state to state.
What Homeowners Should Check Before Buying
Before choosing an insurer, compare more than the premium.
Check the premium
How much will you actually pay each year?
Check the deductible
Can you afford it after a major claim?
Check dwelling coverage
Is the amount enough to rebuild your home?
Check personal property coverage
Are your belongings adequately protected?
Check liability limits
Would the policy provide enough protection if someone were seriously injured?
Check additional living expenses
How much temporary housing coverage is available?
Check exclusions
What major risks are not covered?
Check special deductibles
Some policies have separate deductibles for wind, hurricanes or other specific risks.
Check insurer financial strength
A financially strong insurer may be better positioned to pay claims during major catastrophe events.
Check complaints and claims satisfaction
Price matters, but so does the experience of policyholders when they actually need to file a claim.
Best Home Insurance by Homeowner Type
Best overall: Amica
Best large national insurer: State Farm
Best value: Travelers
Best independent-agent experience: Auto-Owners
Best for claim-free homeowners: Allstate
Best for luxury homes: Chubb
Best for military families: USAA
Best for storm-prone areas: Nationwide
Best for discounts: Farmers
These recommendations are based on 2026 published comparisons and should be treated as a starting point rather than a universal ranking. Insurance availability and pricing can vary by state.
Final Verdict
The best home insurance company in 2026 is not necessarily the cheapest insurer.
For many homeowners, Amica stands out as a strong overall choice based on current 2026 rankings, while State Farm may appeal to consumers who prefer a large national carrier and local-agent access.
Travelers is worth considering for homeowners seeking a balance between cost and service, while Chubb is more appropriate for high-value properties.
Military families should compare USAA, while homeowners who prefer independent agents may want to investigate Auto-Owners.
Most importantly, compare at least three quotes using the same coverage limits and deductibles.
A $200 cheaper policy is not necessarily cheaper if it provides substantially less protection.
Before purchasing, review the declarations page, exclusions, deductibles, replacement-cost provisions and special coverage requirements for your state.
Disclaimer: This article is for informational and educational purposes only and is not insurance, financial or legal advice. Insurance rates, coverage, eligibility, discounts and policy terms vary by state, property and individual circumstances. Always obtain current quotes and review the policy documents directly with the insurer or a licensed insurance professional before purchasing coverage. (*)
Editor : Fanda Yosephta