

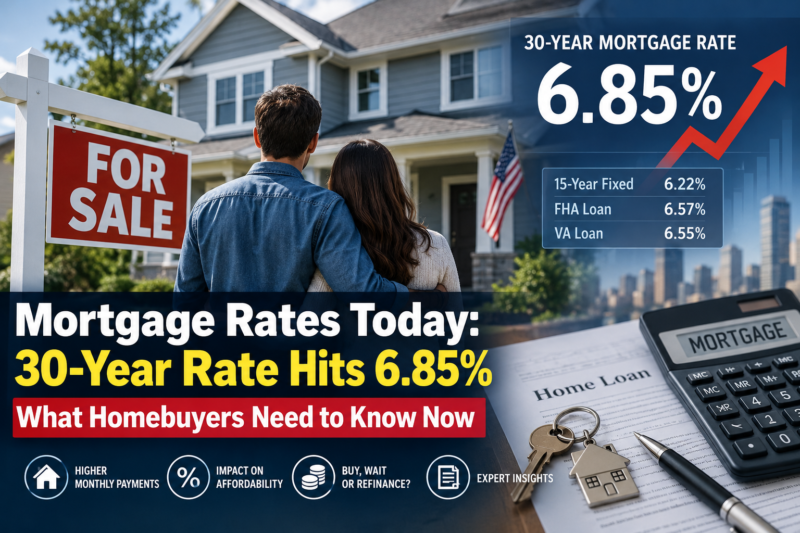
Kayonews-Mortgage rates are climbing again, putting fresh pressure on U.S. homebuyers. The average 30-year fixed mortgage rate reached 6.85% on September 10, 2026, according to Bankrate data, while the average 15-year fixed rate stood at 6.22%.
The latest move matters because mortgage rates directly affect how much Americans pay each month for a home. For buyers already dealing with elevated home prices, even a small increase in the interest rate can significantly change affordability.
Today’s Mortgage Rates
According to Bankrate’s national averages on September 10:
| Mortgage Type | Average Rate |
|---|---|
| 30-year fixed | 6.85% |
| 15-year fixed | 6.22% |
| 30-year FHA | 6.57% |
| 30-year VA | 6.55% |
| 30-year jumbo | 6.91% |
Bankrate’s figures show that the 30-year fixed rate increased 0.05 percentage point compared with the previous week.
Why Are Mortgage Rates Rising?
One of the biggest factors is the rise in longer-term Treasury yields.
Mortgage rates generally move with the bond market, particularly the 10-year Treasury yield. Recent increases in inflation concerns, government borrowing and geopolitical uncertainty have pushed Treasury yields higher, putting upward pressure on borrowing costs.
Oil prices have also become an important factor. Higher energy prices can increase inflation pressure, which could make it harder for the Federal Reserve to lower interest rates.
What Does a 6.85% Mortgage Rate Mean for Buyers?
For a buyer taking out a large mortgage, the interest rate can have a major impact on the monthly principal-and-interest payment.
For example, a $350,000 30-year fixed mortgage at 6.85% would have an estimated principal-and-interest payment of about $2,291 per month.
That figure does not include property taxes, homeowners insurance, HOA fees or maintenance.
This is why buyers should look beyond the advertised mortgage rate and calculate the full monthly cost of homeownership.
Should You Buy a House at 6.85%?
There is no universal answer.
A buyer with stable income, strong credit, sufficient savings and a long-term plan may still find a home affordable at today’s rates.
However, buyers should avoid stretching their budget simply because they qualify for a particular loan amount.
Mortgage rates can change after you purchase, but the home price, property taxes, insurance and other ownership costs can also change.
The better question isn’t simply whether rates are “high” or “low.”
It’s whether the total monthly housing cost fits comfortably within your budget.
Should You Wait for Mortgage Rates to Fall?
Waiting could make sense for some buyers, but it also carries risks.
Mortgage rates could decline in the future, but there is no guarantee about when or by how much. Meanwhile, home prices and inventory can change.
Current forecasts cited by WSJ indicate that mortgage rates could remain above 6% through the end of 2026 rather than returning quickly to the sub-6% levels seen earlier this year.
For buyers who are financially ready, comparing lenders may be more useful than trying to perfectly time the market.
Shop Around Before Choosing a Mortgage
One of the most important steps is to compare multiple mortgage offers.
Bankrate cites research showing that borrowers who fail to shop around can potentially pay substantially more over the life of a mortgage.
Compare:
- Interest rate
- APR
- Closing costs
- Origination fees
- Discount points
- Loan term
- Prepayment terms
- Estimated monthly payment
A mortgage with the lowest advertised rate isn’t necessarily the cheapest loan once all fees are included.
Mortgage Rates and the Federal Reserve
The Federal Reserve does not directly set 30-year mortgage rates.
Instead, mortgage rates are heavily influenced by longer-term bond yields and investor expectations about inflation and monetary policy.
That means even if the Fed changes its benchmark rate, mortgage rates don’t necessarily move by the same amount.
Current inflation concerns and higher Treasury yields remain important factors for the U.S. housing market.
Bottom Line
The 6.85% average 30-year mortgage rate is an important warning for U.S. homebuyers: borrowing costs remain elevated.
Rather than focusing only on whether rates will rise or fall, buyers should compare multiple lenders, calculate the complete monthly housing expense and make sure the payment fits their long-term finances.
For many buyers, getting the best available mortgage offer today may matter more than trying to predict the exact bottom of the rate cycle.
Frequently Asked Questions
What is the mortgage rate today?
The national average for a 30-year fixed mortgage was 6.85% on September 10, 2026, according to Bankrate.
What is today’s 15-year mortgage rate?
The national average 15-year fixed mortgage rate was 6.22%.
Is 6.85% a high mortgage rate?
It is considerably higher than the rates seen during the exceptionally low-rate period of 2020–2021, although it remains below the recent peak reached in late 2023.
Should I buy a home when mortgage rates are 6.85%?
It depends on your income, credit, down payment, home price and overall financial situation. Buyers should calculate the full cost of ownership rather than looking only at the interest rate.
Will mortgage rates fall in 2026?
Rates could move in either direction. Current forecasts cited by WSJ suggest rates may remain above 6% through the end of 2026.
How can I get a lower mortgage rate?
Improve your credit profile, make a larger down payment when practical, compare multiple lenders and evaluate both the interest rate and APR before choosing a loan.(*)