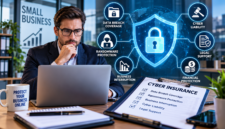


Kayonews-Cyberattacks are no longer a problem limited to large corporations. Small businesses can also face phishing, ransomware, data breaches, payment fraud, and attacks against business networks.
For companies that store customer information or rely heavily on digital systems, cyber insurance can provide another layer of financial protection.
The Federal Trade Commission says cyber insurance can help businesses protect against losses resulting from cyberattacks. Coverage can include first-party losses, third-party liability, and certain costs associated with responding to a cyber incident.
What Is Cyber Insurance?
Cyber insurance is a type of business insurance designed to address certain financial losses associated with cybersecurity incidents.
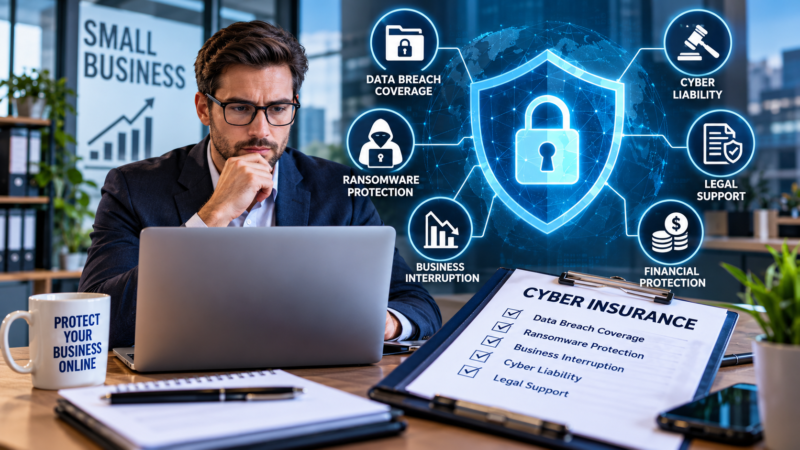
A policy may cover expenses related to a data breach, ransomware incident, business interruption, cyber fraud, legal services, forensic investigations, and claims brought by affected third parties.
However, coverage varies significantly between insurers and policies.
That’s why businesses should examine the policy wording, exclusions, limits, deductibles, and conditions before purchasing coverage.
Why Do Small Businesses Need Cyber Insurance?
Small businesses can hold valuable information even when they have only a few employees.
A business might store:
- Customer names and contact information
- Payment information
- Employee records
- Financial information
- Login credentials
- Business contracts
- Intellectual property
- Supplier information
A successful cyberattack can therefore affect both the company’s technology and its finances.
The FTC notes that cybercriminals target companies of all sizes and recommends that small businesses develop cybersecurity protections and incident-response plans.
What Does Cyber Insurance Cover?
Coverage depends on the policy, but cyber insurance can generally be divided into first-party and third-party coverage.
1. Data Breach Response
A cyber policy may cover certain expenses associated with responding to a data breach.
These can include legal advice, forensic investigations, customer notification, and related response services.
The FTC specifically identifies legal counsel, data recovery, customer notification, call-center services, and forensic services among potential first-party coverage areas.
2. Business Interruption
A cyberattack can temporarily prevent a company from operating normally.
Some cyber policies may cover certain lost income or additional expenses resulting from a covered cyber incident.
Businesses should carefully examine the policy’s definition of a covered interruption and any waiting period or sublimit.
3. Ransomware
Ransomware can lock businesses out of their files and systems.
Cyber insurance may provide coverage related to ransomware response, subject to policy conditions and applicable law.
The FTC warns that paying a ransom does not guarantee that criminals will restore access to data.
Businesses should therefore treat insurance as one component of a broader cybersecurity and recovery strategy.
4. Cyber Extortion
Some policies can provide coverage related to cyber-extortion incidents.
The exact protection may vary, including whether the policy covers negotiation expenses, response services, or certain payments.
Read the policy carefully rather than assuming every ransomware demand is automatically covered.
5. Data Recovery
A cyberattack can damage, encrypt, or delete business data.
Certain policies may cover costs associated with recovering or replacing lost or stolen data.
Businesses should also maintain independent backups because insurance does not replace good cybersecurity practices.
6. Legal and Regulatory Expenses
A data breach can create legal and regulatory obligations.
Depending on the policy, cyber insurance may cover certain legal expenses, litigation costs, and regulatory response expenses.
The FTC recommends that businesses understand their legal and regulatory notification obligations following a breach.
7. Customer Notification
If customer information is compromised, a business may need to notify affected individuals.
Some cyber policies can cover notification services, call centers, and related response expenses.
Requirements vary depending on the type of information involved and applicable jurisdiction.
8. Third-Party Liability
Third-party coverage can become important when another party claims that your business caused or contributed to a cyber-related loss.
Potential situations include claims from customers, business partners, or other affected parties.
The FTC says third-party cyber coverage may include claims, settlements, litigation expenses, regulatory inquiries, and certain damages or judgments.
What Is First-Party Cyber Coverage?
First-party coverage generally addresses losses directly suffered by the insured business.
Potential areas include:
- Data recovery
- Business interruption
- Cyber extortion
- Forensic investigation
- Crisis management
- Customer notification
- Certain fraud losses
- Legal response expenses
The actual coverage depends on the policy.
What Is Third-Party Cyber Coverage?
Third-party coverage generally addresses liability arising from claims brought by other parties.
For example, a customer could claim that a data breach involving the business exposed their personal information.
A cyber liability policy may provide defense and other covered expenses, depending on the terms.
How Much Does Cyber Insurance Cost?
There is no universal cyber insurance price for every small business.
Premiums can depend on factors such as:
- Industry
- Annual revenue
- Number of employees
- Amount and type of data stored
- Security controls
- Previous cyber incidents
- Policy limits
- Deductible
- Coverage options
- Business operations
A company that stores large amounts of sensitive customer data can present a different risk profile from a small business with limited digital operations.
For this reason, businesses should obtain multiple cyber insurance quotes rather than relying on a generic online price.
What Can Make Cyber Insurance More Expensive?
Insurers may pay close attention to the company’s cybersecurity controls.
Risk factors can include:
- No multi-factor authentication
- Weak password policies
- Outdated software
- Poor backup procedures
- Lack of employee training
- Weak access controls
- Previous breaches
- Large volumes of sensitive data
The FTC recommends measures such as multi-factor authentication, regular software updates, data backups, encryption, access controls, and employee training.
How to Get Cheaper Cyber Insurance
Businesses can potentially improve their insurance options by strengthening cybersecurity before requesting quotes.
Consider implementing:
- Multi-factor authentication
- Regular data backups
- Endpoint security
- Software patching
- Employee security training
- Strong access controls
- Incident-response procedures
- Vendor security reviews
- Encryption for sensitive information
- Regular security assessments
Better cybersecurity does not guarantee a lower premium, but it can help demonstrate that the business is actively managing cyber risk.
What Should You Look for in a Cyber Insurance Policy?
Before purchasing a policy, ask the insurer or broker:
- What cyber incidents are covered?
- Does the policy cover ransomware?
- Is business interruption included?
- Does it cover data restoration?
- Are forensic services covered?
- Does it include legal defense?
- Is regulatory response covered?
- Does it provide third-party liability coverage?
- What are the policy limits?
- What are the deductibles?
- Are there sublimits?
- What exclusions apply?
- Are vendor-related breaches covered?
- Is social engineering or funds-transfer fraud covered?
The FTC specifically recommends checking whether policies cover attacks involving data held by vendors and third parties and whether the policy provides appropriate defense and response services.
Cyber Insurance Does Not Replace Cybersecurity
Buying cyber insurance should not be treated as a substitute for cybersecurity.
Businesses should continue to:
- Back up critical information
- Require multi-factor authentication
- Train employees
- Update software
- Limit access to sensitive data
- Monitor systems
- Maintain an incident-response plan
The FTC recommends these types of safeguards as part of a broader cybersecurity program.
Cyber Insurance vs General Business Insurance
General business insurance may cover certain traditional risks, but cyber-related losses can involve specialized exclusions and coverage requirements.
A business should not assume its existing commercial policy covers every cyber incident.
Ask your insurance professional to explain how existing policies interact with proposed cyber coverage.
FAQ: Cyber Insurance for Small Business
Is cyber insurance worth it for a small business?
It depends on the company’s risk exposure, data, operations, existing insurance, cybersecurity controls, and ability to absorb losses.
Does cyber insurance cover ransomware?
Some policies provide ransomware-related coverage, but terms, exclusions, limits, and conditions vary.
Does cyber insurance cover data breaches?
Many cyber policies offer data-breach coverage, including certain response, legal, forensic, notification, and recovery expenses.
How much does cyber insurance cost?
There is no standard price. Premiums depend on the business’s size, industry, cybersecurity controls, claims history, coverage limits, and other risk factors.
Does general liability insurance cover cyberattacks?
Not necessarily. Businesses should review their existing policy and ask their insurer specifically about cyber-related exclusions and coverage.
Can cyber insurance cover business interruption?
Some policies provide business-interruption coverage following a covered cyber incident. Check the policy definition, waiting period, limits, and exclusions.
Does cyber insurance cover vendor data breaches?
Some policies can cover cyber incidents involving third-party or vendor-held data, but this must be confirmed in the policy wording.
Bottom Line
Cyber insurance for small business can help manage the financial consequences of certain cyber incidents, including data breaches, ransomware, business interruption, forensic investigations, legal expenses, and third-party claims.
But coverage differs substantially between policies.
Before buying cyber insurance quotes, compare coverage limits, deductibles, exclusions, ransomware protection, business-interruption coverage, data-breach response, third-party liability, and vendor-related incidents.
The strongest strategy combines cyber insurance with effective cybersecurity controls. Insurance can help transfer some financial risk, while prevention and preparation can reduce the likelihood and impact of an attack. (*)
Editor : Fanda Yosephta