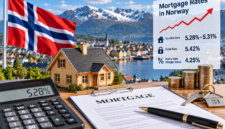


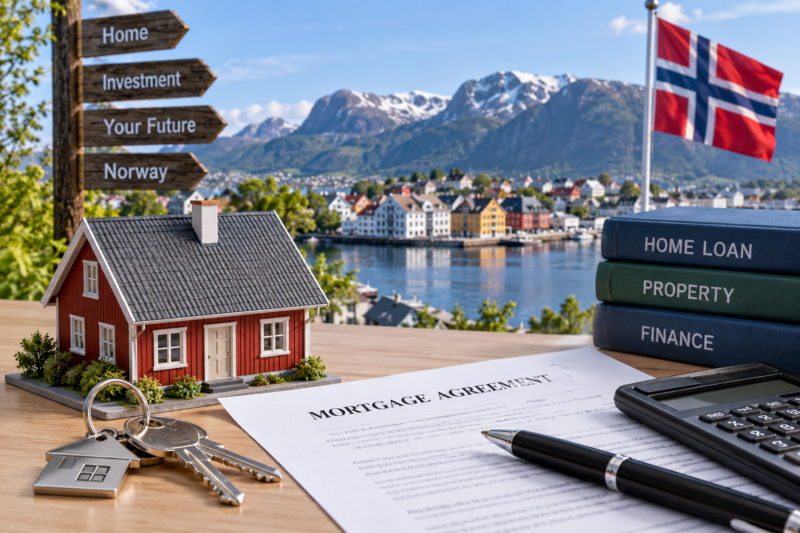
Kayonews-Buying a home in Norway is a major financial decision. For many buyers, a mortgage is the main way to finance the purchase.
A Norway mortgage is a loan secured against residential property. The bank normally evaluates your income, existing debt, expenses and the value of the property before approving the loan.
How Does a Mortgage Work in Norway?
Norwegian banks assess whether you can afford the mortgage before approving your application. The assessment considers your income, total debt and regular living expenses.
Banks also consider how your finances would handle higher interest costs. Norwegian mortgage rules require lenders to assess debt-servicing capacity against a significant increase in the interest rate.
The amount you can borrow therefore depends on more than the property’s purchase price. Your income, existing loans, financial commitments and available equity can all affect the bank’s decision.
How Much Deposit Do You Need?
The maximum loan-to-value framework is an important part of the Norwegian mortgage market. Finanstilsynet reported that the maximum LTV requirement was increased from 85% to 90% in December 2024.
This means a buyer may potentially finance a large share of a property’s value through a mortgage, subject to the bank’s assessment and applicable rules.
For example, if a property costs NOK 5 million, 90% financing would correspond to NOK 4.5 million. The remaining NOK 500,000 would represent 10% of the purchase price.
However, buyers should also budget for transaction costs and other expenses associated with purchasing property.
What Determines Your Mortgage Interest Rate?
The interest rate offered by a Norwegian bank can depend on several factors.
These may include the size of the mortgage, the property’s value, your income, debt level, financial history and the bank’s pricing.
Mortgage rates can also change when market conditions change. Therefore, borrowers should compare the effective cost of different mortgage offers rather than looking only at the advertised interest rate.
Fixed or Variable Mortgage Rates
Homebuyers may encounter both variable and fixed-rate mortgage options.
A variable rate can change during the loan period. This means monthly payments can increase when interest rates rise.
A fixed-rate mortgage can provide greater payment predictability during the fixed period. However, the terms and potential costs should be reviewed carefully before signing.
Norwegian authorities have also highlighted issues surrounding interest-rate adjustment clauses in variable-rate mortgage agreements.
Mortgage and Tax Deductions in Norway
Mortgage interest can have tax implications for borrowers in Norway.
The Norwegian Tax Administration states that taxpayers can generally claim a deduction for interest paid on debt, including mortgage interest.
Mortgage and interest information is normally reported by banks and can appear in the tax return. Borrowers should check that the reported figures are correct.
For joint mortgages, borrowers should also check that the allocation of debt and interest is correctly reported.
Can Foreigners Get a Mortgage in Norway?
Foreigners may be able to obtain mortgage financing in Norway, but approval depends on the lender’s assessment and the borrower’s circumstances.
Banks can consider factors such as Norwegian income, employment, residence status, existing debt and the property being purchased.
Foreign buyers should therefore contact several lenders and ask about their specific requirements before making a property purchase.
How to Apply for a Mortgage in Norway
The process generally starts by reviewing your finances and determining how much you can afford.
You can then compare mortgage offers from different banks. After choosing a lender, the bank evaluates your financial situation and the property.
A typical application may require documentation relating to income, employment, existing debt and other financial information.
Before accepting an offer, compare the interest rate, fees, repayment period and total borrowing cost.
How to Reduce Mortgage Costs
One way to reduce borrowing costs is to compare offers from multiple banks.
You can also review your mortgage when market conditions change. A lower interest rate can make a significant difference over a long repayment period.
Borrowers should also monitor their debt level and avoid taking on additional debt that could make monthly payments difficult.
If refinancing is considered, remember that refinancing-related expenses can have tax implications. The Norwegian Tax Administration provides specific guidance on deductible refinancing expenses.
Norway Mortgage Calculator
A mortgage calculator can help estimate monthly payments before you apply for financing.
For example, a borrower can enter:
- Property price
- Down payment
- Mortgage amount
- Interest rate
- Repayment period
The resulting payment is only an estimate. Actual payments can differ because banks may use different rates, fees and repayment structures.
Frequently Asked Questions
What is a mortgage in Norway?
A mortgage is a loan used to finance property purchases and secured against the property.
How much can I borrow for a home in Norway?
The amount depends on factors such as income, existing debt, expenses, property value and the lender’s credit assessment.
Can foreigners get a mortgage in Norway?
Foreigners may qualify, but each bank applies its own lending assessment and requirements.
Is mortgage interest tax deductible in Norway?
Generally, interest paid on debt can qualify for a tax deduction. Borrowers should check their tax information and current rules.
Should I choose a fixed or variable mortgage?
It depends on your financial circumstances and preference for payment certainty versus exposure to changing interest rates.
Can I refinance a mortgage in Norway?
Refinancing may be possible depending on the lender and your financial situation. Borrowers should compare the potential savings with refinancing costs.
What should I compare before choosing a mortgage?
Compare the interest rate, effective borrowing cost, fees, repayment period, flexibility and conditions attached to the mortgage.
Final Thoughts
A Norway mortgage can make homeownership more accessible, but borrowers should understand the total cost before signing a loan agreement.
Compare several mortgage offers, review your borrowing capacity and consider how higher interest rates could affect your monthly budget.
For the latest requirements, borrowers should verify the rules with their bank and Norwegian authorities before applying.(*)
Editor : Fanda Yosephta